

How much does it cost to sell a property at auction? A guide for UK property owners. How much does it cost to sell a property at auction and how do the sale costs compare to an estate agency sale? Find out about the costs for selling your house or flat at auction and how to save money by passing some of your costs to the buyer.
How much are property auction fees?
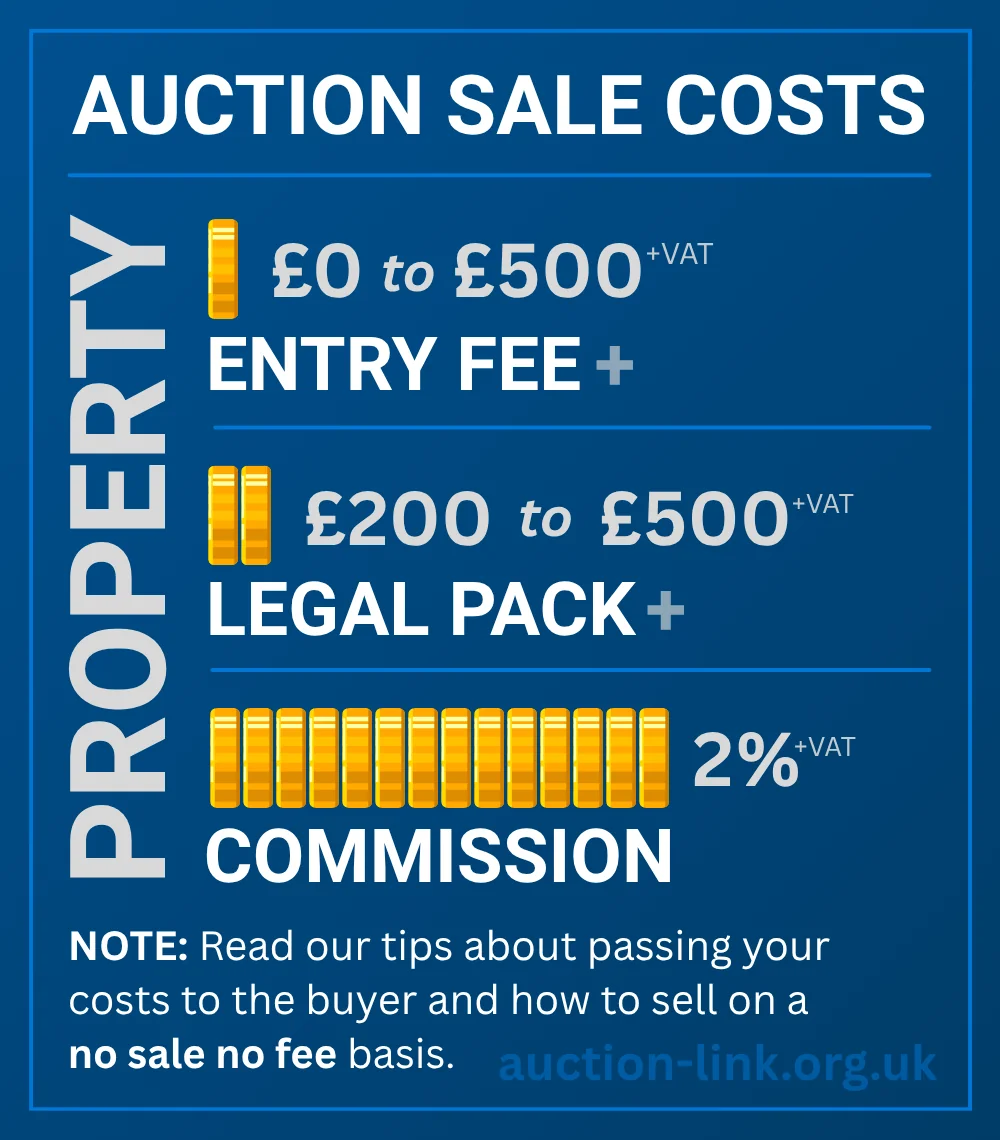
Selling a property at auction costs less than most people think. The total cost is about the same you would expect to pay a traditional high street estate agent. There are 3 costs to consider when selling a property at auction:
- (1) COMMISSION - The auctioneers commission is around 2% to 3% + VAT of the final sale price and that's only paid when the property successfully sells.
- (2) ENTRY FEE - Most auctioneers request an upfront catalogue/entry fee of around £300 + VAT or more, but it may be possible to postpone payment until after the property has successfully sold.
- (3) AUCTION LEGAL PACK - The seller's solicitor is responsible for preparing the auction legal pack at the cost of £200 or more, which is payable before the auction.
It's worth knowing that the legal pack will not always mean an additional cost. If you have already been through a private treaty (estate agency) sale that fell through, your solicitor can often reuse the documents they prepared, so there may be little or nothing extra to pay.
Some auctioneers will also arrange the legal pack for you with no upfront payment, with the cost deducted or settled once the property successfully sells.
Timing is important too. Most auction selling costs only become payable after the property has sold, which can make the overall cost much easier to manage and budget for.

Passing your auction sale costs to the buyer
A key benefit of selling at auction is the complete control the seller has over the contract of sale, there's no input from the buyer. This means the seller can dictate terms like the completion date, responsibilities of the buyer after exchange and any extra costs to be paid by the buyer.
By adding a simple clause to the contract of sale it's possible to pass all (or part) of your auction costs and legal fees to the buyer, in fact it's standard practice for regular auction sellers (e.g. property traders, banks and local authorities). Some buyers will not bid as high for the property if they spot the clause in the legal pack, but others will not worry.

If you want to do this, let your solicitor know as early as possible. The clause should be included in the special conditions of sale and, ideally, be in place from the moment the legal pack goes live.
It can be added later if necessary, but it is good practice to have the special conditions settled before buyers begin reviewing the pack. Changes close to auction day can unsettle bidders, particularly if they have already worked out their maximum bid based on the original terms.
It is also worth checking with the auction company. Although this is common practice, some auctioneers may not allow it, so it is better to raise the point early rather than assume it will be accepted.
Negotiating sales commission with the auctioneer
The starting rate for an auctioneer's commission is typically 2% to 3% + VAT and that's only paid when the property successfully sells. So if a property sells for £200,000 the commission payable to the auctioneer at 2% would be £4,000 + VAT.
You can save money by passing costs to the buyer. And some auctioneers offer a no sale no fee service.
For higher value or particularly saleable properties the auctioneer might be prepared to reduce their commission, but there is a lot of organising and marketing that takes place for the auctioneer to be able to justify their fee.
Auctioneers usually charge a minimum selling fee of anything from £1,500 upwards, so if a low value property (such as a garage) sells for £10,000 the 2% commission rate will not apply, otherwise the fee would only be £200. Instead the auctioneer will charge the minimum selling fee.
TIP: Compared to some of the newer methods of selling, such as paying an online estate agent a fixed fee, selling a property at auction may seem relatively expensive. So it's worth a quick cost benefit analysis to see if auction will pay off for you.
How much does it cost to prepare the auction legal pack?
The auction legal pack is crucial for the successful sale of a property at auction, it contains all the legal information (e.g. land registry documents, deeds, searches, property information questionnaires, lease documents, tenancy agreements etc) relating to the property. So the more information there is in the legal pack the more confident prospective buyers will be when bidding on auction day. It's therefore important not to cut costs when preparing the legal pack as it may adversely affect the final sale price. Costs for preparing an auction legal pack for a freehold property can be anything from £200 upwards. For a leasehold property the cost of obtaining the management information pack from the freeholder/landlord will add another £200 or more.
Most of these legal costs are not unique to selling at auction. When selling through an estate agent or privately the seller will also need to prepare legal documents for the prospective buyer. It's only the searches (local authority search, water search etc) that are obtained by the buyer in the case of an estate agency sale, but by the seller in the case of an auction sale.
Who pays for the survey?
We're occasionally asked whether the seller needs to include a survey report for their property in the auction legal pack. The survey report is NOT the responsibility of seller. There is no expectation for a survey report to be included in the auction legal pack.
Many of the buyers at auction are cash buyers, so will not require a survey. However, if the buyer does require a survey, they will need to have sorted that out (and seen the report) before bid on auction day. With an unconditional auction sale, the buyer is bidding to buy - full stop! They're not bidding to buy subject to contract or survey.
Costs for selling a house by auction?
Request a free valuation and auction sale cost estimate for your property today. In some cases we may need a few more details about your property before providing a free and no-obligation auction sale estimate.
Free EstimateCosts for cancelling or withdrawing from auction
If you've booked your property into auction, but then have a change of plan, you may be liable to paying the auctioneers withdrawal fee if you decide to back out of the auction sale. Auction withdrawal fees vary, but can be as much as the full commission rate you would have been liable to pay if your property had successfully sold.
It's worth noting that if you signed the auctioneers' terms remotely (i.e. not in the auctioneers office) there will usually be a 14 day cooling off period. However, since the timescales for selling at auction are very quick, the auctioneer might ask you to tick a box on the auction contract that waives your right to cancel, in order for them to commence their service immediately, and begin marketing your property as soon as possible.
Other costs to consider when selling a property at auction
As with selling a property through an estate agent or privately, there are other costs to be considered when selling a property, they include; legal fees, moving costs and taxes that might be due. For example capital gains tax on buy-to-let properties and inheritance taxes for probate sale. Also consider whether any early redemption penalties might be due on your mortgage or secured loans. These are all payments your solicitor will be able to help you calculate when determining your bottom line sale price i.e. your reserve price.
If the property doesn't sell at auction there will usually not be any costs or obligations to the seller, unless stated in the auctioneers terms.
Are there any costs to pay if a property fails to sell at auction?
Just like selling through a traditional high street estate agent, the auctioneers commission works on a "no sale no fee basis". So the sales commission is only payable when the property is sold and contacts are exchanged, without that happening the auctioneer won't charge their fee. If a property fails to sell the only costs incurred by the seller would be their legal fees (for preparation of the auction legal pack) and any entry/catalogue fee that may have been paid before the auction.

A property that goes unsold at auction is treated differently from one that you withdraw beforehand. Withdrawing can sometimes trigger a separate fee, which may be as much as the commission you would have paid if the property had sold. By contrast, if the property simply fails to reach its reserve price, there is usually nothing further to pay.
Cost benefit analysis - is it worth selling at auction?
With so many low-cost online estate agents to choose from, does an auction sale provide value for money? Apart from the speed and reliability an auction sale offers, from a purely financial perspective, is it worth it? Can you achieve a higher sale price at auction compared to any other method of sale? The answer depends on the type of property being sold, some properties sell for considerably more at auction compared to estate agency sales due to two key features of auction; competition and transparency.

Competition
Property developers, amateur DIYer's and ambitious owner occupiers will compete to buy a property at auction in the knowledge they'll be able to refurbish it cost-effectively and either sell on for a profit or live there themselves. The key word being compete. In an auction environment, where the price can only go one way (up) it's the competitive bidding environment that drives the price up.
Transparency
In a closed/private sale environment, such as an estate agent sale (also known as a "private treaty" sale) the estate agent has a high level of influence over negotiations. If after a few months of marketing a property the estate agent tells the seller that £100,000 is a fair price, the seller will probably be inclined to accept an offer around that level. By keeping the property in the hands of one or two estate agents the sale lacks transparency.
In fact, a highly lucrative market exists for property traders who purchase problem properties through estate agents one week and flip them at auction the next week - the properties are sold for considerably higher prices as "properties with potential" in the transparent and competitive bidding environment that's found at public auction.
Ready for auction?
Request a free valuation and reserve price estimate for your property today. In some cases we may need a few more details about your property before providing a free and no-obligation auction sale estimate.
Free EstimateQuestions and Answers
Do properties sell for lower prices at auction?
Some types of property are particularly well suited to sale by auction; properties in need of modernisation or with potential are ideal for auction and will achieve a higher sale price at auction compared to an estate agency sale. But properties with their potential exhausted will usually sell for more by private treaty (estate agency) sale, unless the property is unique or in a very good location, in which case the top price may be found through competitive bidding at auction.
What happens if an auction property doesn't sell?
Most properties do successfully sell at auction, it's considered the most reliable method of sale. If bidding doesn't reach the reserve price on auction day your property will be made available as an unsold lot. The auction company will contact all interested buyers and ask for their best and final offers. If a property doesn't sell first time around it can be entered into a subsequent auction, that might be 4 or 6 weeks later.
What costs are paid upfront and after an auction sale?
The costs for selling at auction works out to be about the same as using a good high street estate agent. Commission at around 2% to 3% + VAT if the final sale price is only payable on successful sale. Some auctioneers charge an upfront entry fee of £200 to £500, but this can be negotiable and only payable after sale.
How quickly can a property be sold at auction?
Legal exchange of contracts can take place within 3 to 4 weeks, with completion of sale a further 4 weeks later. Timings are flexible; if a seller needs to complete sooner or later, they can ask their solicitor to shorten or extend the completion date.
How do you find a good local property auctioneer?
There are hundreds of property auctioneers in the UK. The best suited auctioneer for your property will depend on the property type and location. Looking at the past auction results (usually available on the auctioneer's website) can be a good starting point to short list a suitable auctioneer.
Popular auction resources
- Guide to selling your house at auction
- Risks and disadvantages of auction sales
- Frequently asked questions
- Online property auction sale costs
- Request an auction sale price estimate
Next steps...
Why not request a free pre-auction appraisal for your property? It only takes a few seconds. Or feel free to call us on 0800 862 0206 if you have any questions.
UK Property Market Update: October 2026
On 28 October the Chancellor delivers the Autumn Budget, and the property market spent September bracing for it. Stamp duty changes have been ruled out, but a rise in capital gains tax (possibly aligning it with income tax), the end of the CGT “uplift” on death and a lower starting point for the new high-value council tax surcharge are all being openly modelled. The effect is visible in the auction room already: Savills released its largest September catalogue ever, 380 lots, and its auctioneers said many investors simply want to complete before the year is out.
The other story this autumn is borrowing costs, which are going the wrong way. Average mortgage fixes have climbed to their highest levels in two years, the 10-year gilt yield touched 5.5% for the first time since 2007, and money markets are now pricing in Bank of England rate rises rather than cuts. Buyers have not disappeared, but there are fewer of them, they have more to choose from, and they are extremely price-sensitive. Nationwide's annual house price growth halved in September to 0.8%, the weakest reading since last December.
House prices and activity
The main indices now agree on the direction of travel. Nationwide puts the average home at £274,251 in September, down 0.2% on the month and up just 0.8% on the year. Zoopla's latest index also shows 0.8% annual growth, on an average of £273,000, with sales agreed running 9% below last year and the number of homes for sale 5% higher. Lloyds (the renamed Halifax index) recorded the first annual fall since November 2023 in its August figures, down 0.4% to £298,468, with Greater London 1.5% lower over the year. The official ONS index for July has London prices down 3.3% on the year at £569,000, the weakest reading since January 2024, while Wales and Scotland are still growing at more than 2%.
London is where the gap between asking and selling is widest. Rightmove reports that only 42% of London homes listed find a buyer, against 91% in Scotland, and that a London seller waits 78 days on average for an offer compared with 33 north of the border. Zoopla's figures tell the same story: just 30% of London homes sell within three months, flats are down 1.3% nationally and have fallen in nine of eleven regions, and London has the steepest regional price fall at minus 1%. Nationally, Rightmove's average asking price did rise 0.7% in September to £367,440, the first increase since May, but the firm itself calls it “a modest recovery rather than a major turning point” with “a large crowd of sellers chasing a smaller number of buyers”. The number of homes for sale remains at a 12-year high for the time of year.
Interest rates
On 17 September the Bank of England held the base rate at 3.75% by a 6-3 vote, with Megan Greene, Catherine Mann and Huw Pill all voting for a rise to 4%. The Governor warned that the longer energy price volatility persists, “the more likely it is we will need to raise Bank Rate”, and the Bank's own projection now has inflation at around 3.75% by the end of this year and slightly above 4% in early 2027. The next decision is on 5 November, a week after the Budget. Markets are pricing in roughly four quarter-point increases by the end of 2027, and several forecasters expect the first of them in November. Gilt yields have moved accordingly, with the 30-year above 6% for the first time since 1998, and it is these market rates, not the base rate, that set the price of a fixed mortgage.
Inflation
CPI inflation rose to 3.1% in the year to August, up from 2.9% in July, with motor fuel the biggest culprit: petrol and diesel are 23% dearer than a year ago, with petrol averaging 161p a litre. Core inflation held at 2.6%, which is some comfort, but the energy picture is not improving. Ofgem's price cap rose a further 4% on 1 October to £1,723 for a typical household, and Cornwall Insight is forecasting a 16% jump in January, the largest in four years, if wholesale gas stays where it is. The September CPI figure arrives on 21 October, exactly a week before the Budget, and will shape both the Chancellor's room for manoeuvre and the Bank's November vote.
Mortgages
September was the worst month for mortgage pricing in a long while. Moneyfacts' average two-year fix reached 5.91% and the five-year 5.94% on 23 September, the highest since July 2024 and October 2023 respectively, up from around 5.6% in mid-August. Two-year swap rates, which drive fixed-rate pricing, rose from about 3.3% in late February to more than 4.2% in early September, and NatWest, Santander, HSBC, Lloyds, TSB and Nationwide all raised their fixed rates twice during the month. Rightmove estimates that a typical new borrower now pays around £180 a month more than before the Middle East conflict began. There are occasional cuts (NatWest trimmed some rates in the last week of September), but anyone coming off a fixed deal in the next six months should speak to a broker now rather than wait for the market to turn.
What does this mean for property auctions?
The auction season restarted in September with strong catalogues and respectable results. Allsop's residential sale on 16 and 17 September raised £37.6 million at a 72% success rate, Barnard Marcus offered 323 lots on 10 September and raised £35.7 million, and Savills' two September sales are the largest the firm has held in that month. Auction House, named Auction House of the Year at the National Property Awards, reports lots sold up more than 10% and funds raised up more than 13% across the first eight months of the year. The Essential Information Group's rolling 12-month figures show 30,826 lots sold, up 9.4% on the previous year, raising £6.1 billion. London is the fastest-growing region, with lots offered up 31% and lots sold up 35%. August itself, as usual, was quiet, with 1,084 lots sold at a 60.6% success rate.
Why is auction stock rising while the wider market stalls? Partly because selling through an estate agent has rarely been slower or less certain. Fall-throughs rose 6.6% in the second quarter to almost 72,000 failed sales, costing the average seller £3,584 in wasted fees, and London sellers are waiting two and a half months just for an offer. At auction, the sale is legally binding on the fall of the hammer and completes within weeks, typically 20 working days. A lot sold at an October or November sale will have completed before Christmas, whatever the Budget contains, and nobody can come back to renegotiate the price when their mortgage offer changes.
Landlords are the other big source of new entries. Nearly two-thirds of letting agents say rental supply has fallen since the Renters' Rights Act took effect in May, and 91% of them blame landlords selling up. Savills' own research found 30% of landlords more likely to dispose of property within two years, rising to 54% of those with a mortgage, and the extra two percentage points on rental income tax from April 2027 is already on the statute book. NAVA Propertymark's third-quarter report notes that vacant houses and flats in need of modernisation remain the most sought-after lots in the room, with landlords increasingly pivoting towards commercial stock. If you own a tired property with a tenant in place, or a vacant one you cannot afford to refurbish, there has rarely been a better-informed audience of buyers waiting for it.
Our advice is simple. If you want your sale completed before the end of the year, instruct an auctioneer early (entries usually close about four weeks before auction day). Set a realistic reserve: auction buyers are just as price-sensitive as buyers on the portals, and a sensible reserve is what gets them bidding against each other. And remember that in a market where only four in ten London homes find a buyer at all, a legally binding sale on a fixed date is worth a great deal.